Table of Contents
The Dilemma of Declining Global PC Shipments Amid Rising Component Costs
As the world grapples with the aftermath of a global pandemic, the PC industry is facing a crisis of its own. The latest data reveals a staggering 21% decline in global PC shipments in Q3, with a further 27% drop predicted for Q4. This downward spiral is attributed to the relentless surge in memory and component prices, which show no signs of abating.
The Unprecedented Plunge in PC Shipments
The PC market is currently enduring unprecedented challenges, with memory prices skyrocketing and component costs escalating in tandem. The relentless demand for AI technologies has further strained the supply chain, leading to a severe downturn in the market. Each quarter in 2026 has witnessed a significant decline in shipments, culminating in a 21% drop in Q3 compared to the previous year.
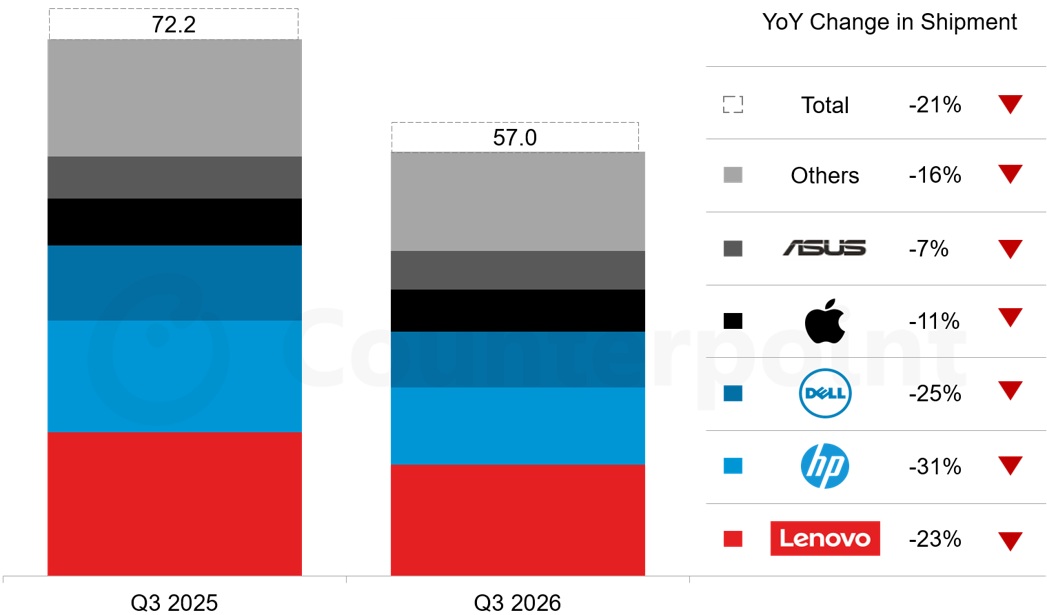
All major PC vendors, including Lenovo, HP, Dell, Apple, and ASUS, have recorded double-digit declines in shipments, with HP experiencing the most significant drop at 31%. Lenovo, the market leader, saw a 23% decline, highlighting the widespread impact of the industry crisis.
The Landscape of PC Vendors in Q3 2026
- Lenovo: Despite a 23% decline in shipments, Lenovo maintained its market leadership with a 26.3% share.
- HP: The second-largest vendor saw a 31% drop in shipments, impacting its market share significantly.
- Dell: Dell’s shipments fell by 25%, showcasing the challenges faced by commercial demand in the current market scenario.
- Apple: Apple’s shipments declined by 11%, with the MacBook Neo helping cushion the impact.
- ASUS: ASUS experienced a 7% decline in shipments but managed to increase its market share.
The Bleak Outlook for Q4 and Beyond
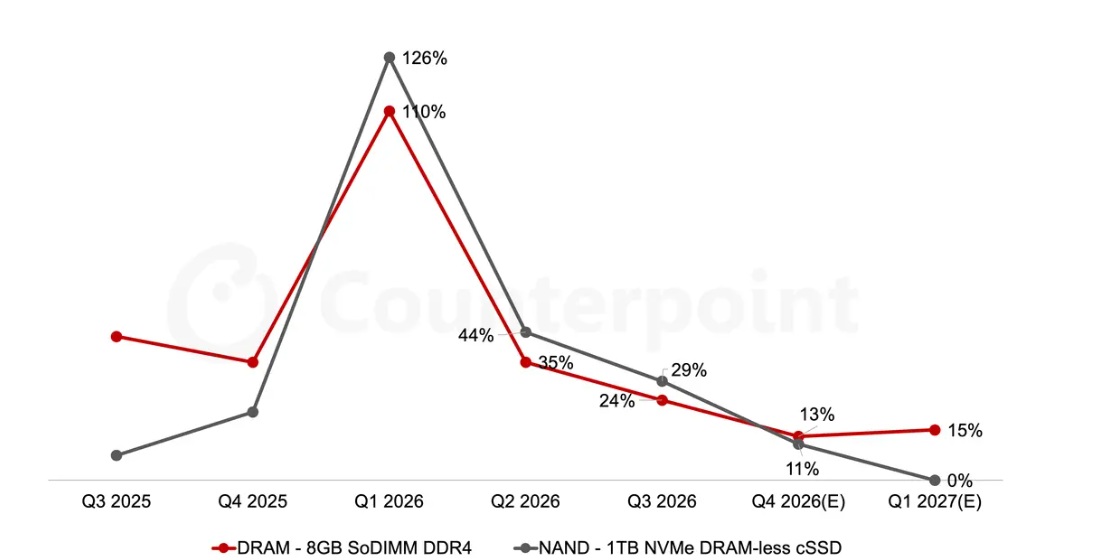
As the industry braces for further challenges, Q4 2026 is projected to witness a 27% decline in PC shipments. The escalating prices of components are making it harder for consumers to justify PC replacements, exacerbating the market contraction. While commercial demand offers some respite, it is insufficient to offset the broader downturn.
Senior Analyst Minsoo Kang highlighted the mounting pressure on the global PC market due to rising costs and weakening demand. Differentiated product portfolios and competitive positioning have enabled some vendors to weather the storm, but affordability remains a critical factor in purchasing decisions.
Counterpoint Research predicts a stabilization of PC shipments in 2027 at a lower volume level, signaling a period of structural adjustment for the industry.
Associate Director David Naranjo emphasized the need for OEMs to strike a balance between margins and affordability in the face of deteriorating consumer demand. Innovation, competitive pricing, and compelling value propositions will be key to navigating the turbulent market landscape.
Despite the hopeful outlook for a softening of component prices in 2027, the industry faces a long road to recovery. The PC market’s resilience will be tested as vendors strive to adapt to the evolving dynamics of supply and demand.
The PC industry is at a crossroads, with challenges and opportunities on the horizon. As the market undergoes a period of transformation, stakeholders must adapt and innovate to thrive in a rapidly changing landscape.